HAMILTON CO. SEPT 2026 MEDIAN SALE $485,000 ▼2.6%DAYS TO CONTRACT 25 ▲56%SUPPLY 2.1 MO ▲7.5%SALE-TO-LIST 98.4% ▼0.4%HOMES FOR SALE 1,018 ▲7.5%$/SQ FT $190 ▲4.4%
Buyers

Buying a home in Hamilton County, without the guesswork.

You’ll know what I know: the comps, the fine print, every deadline, and what a house will really need. Here’s exactly how it works.
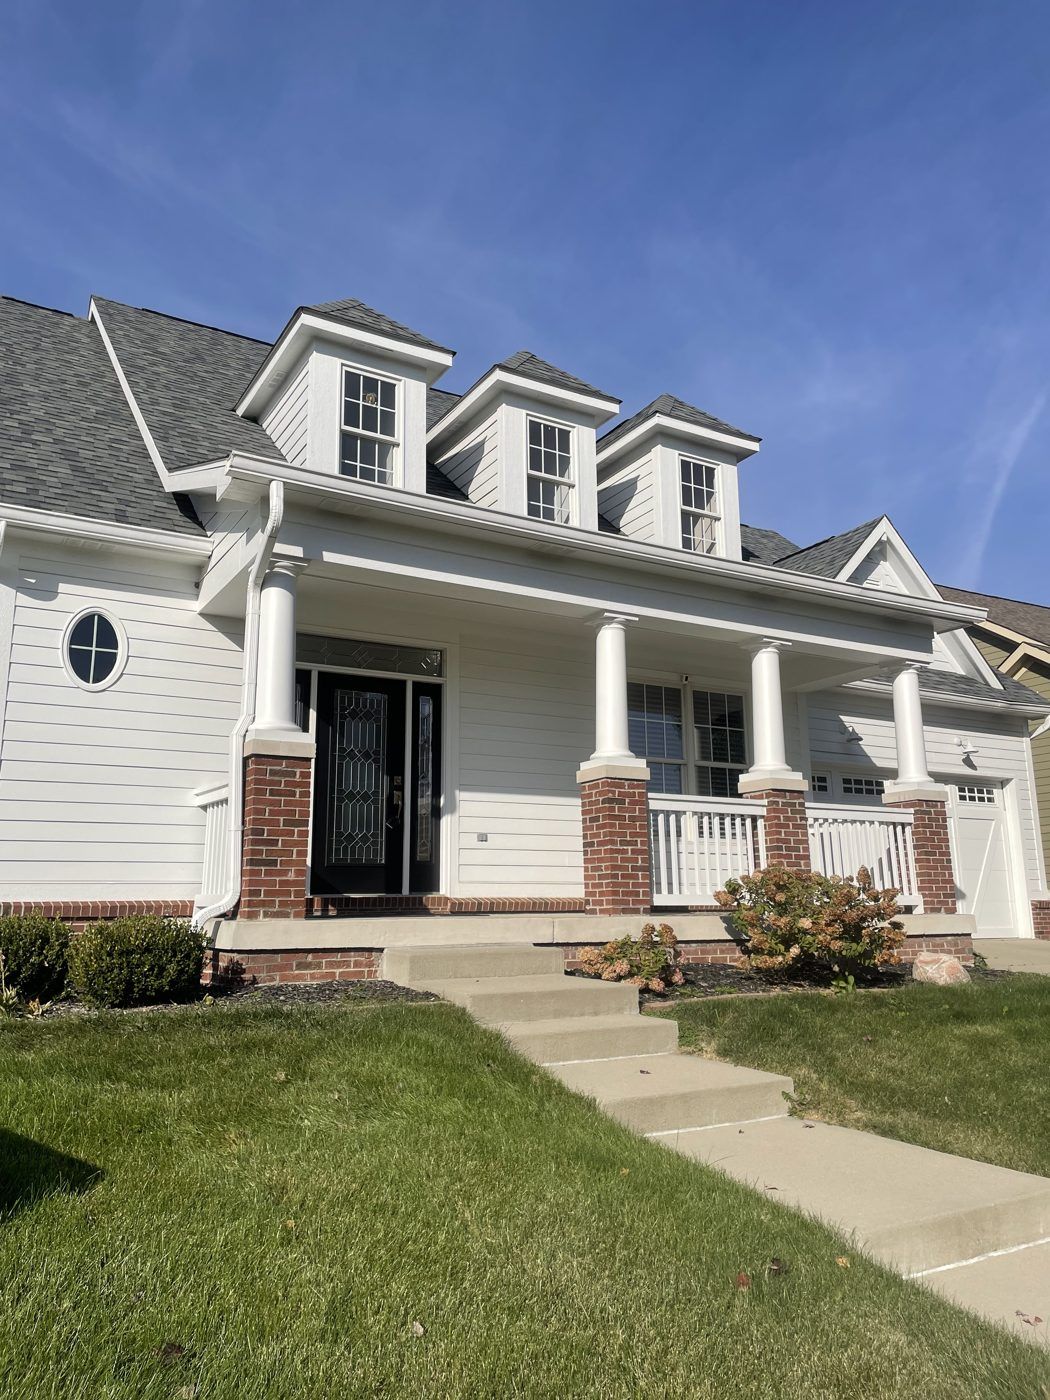
A two-story home with a covered front porch in Saxony, Fishers
How I work with buyers

Six steps. No surprises.

01A quick intro callFifteen minutes on your timeline, budget, and must-haves. No pressure, no pitch.
02Get pre-approvedI’ll connect you with a lender I trust so you know your real number before you fall for a house.
03Search smarterA RealScout search built around you, plus my read on every listing: what’s great, what’s overpriced, what needs work.
04Tour in person or on videoCan’t make it? I’ll walk the home on a private video and point out what photos hide.
05Offer and negotiateReal comps, a call to the listing agent for intel, and terms that protect you, not just a price.
06Contract to keysInspection, appraisal, financing, and every deadline tracked and explained. Then I’m still your agent after closing.
Same business dayEvery call, text, and email
Weekly check-insEven when nothing’s new
Rehab estimatesA rough cost when a home needs work
Fine print, readHOA rules, disclosures, title
Getting ready to buy

Your ready-to-buy checklist.

Eight things to do before you start touring. Most buyers get through the whole list in a couple of weeks.

See printable guides A kitchen island with a granite countertop
Check your creditPull your free reports and fix any errors before a lender sees them.
Know your monthly comfort zonePick a payment you can live with, not the maximum a lender approves.
Save for the down payment and closing costsClosing costs are separate from the down payment. Your lender will estimate them.
Gather your documentsPay stubs, W-2s or tax returns, bank statements, and ID, all in one folder.
Get pre-approvedA real letter with a real number. More on that below.
Sign a buyer agreement with meRequired before touring. It spells out what I do and how I’m paid, in writing.
Set up your RealScout searchNew listings that match, the moment they hit the market.
Write your must-haves vs. nice-to-havesIt makes every showing faster and every decision easier.
Pre-approval

Pre-qualified isn’t pre-approved.

They sound alike. Sellers treat them very differently.

Get a lender introduction
Pre-qualified
  • A quick estimate based on what you tell the lender
  • Usually no documents and no full credit review
  • Good for a rough budget, weak in a negotiation
Pre-approved what you want
  • The lender verifies income, assets, and credit
  • You get a letter with a real number on it
  • Sellers take your offer seriously, and you know your true budget
What to bring

Recent pay stubs, two years of W-2s or tax returns, two months of bank statements, and a photo ID.

How long it takes

Often a few days once your documents are in. Your lender will give you the real timeline.

Protect it

No new credit cards, car loans, or big purchases until after closing. Ask your lender first.

Mortgage calculator

What would my payment be?

$450,000
10%
6.25%
Loan term
For illustration onlyThis calculator is a rough estimate for planning, not a loan offer, pre-approval, or quote. Your actual rate, payment, mortgage insurance, and closing costs depend on your credit, loan type (conventional, FHA, VA, USDA), lender, and the home itself. Confirm every number with a licensed lender.Indiana caps property tax on a primary residence (homestead) at 1% of assessed value, and at 2% for rentals and second homes. Actual bills vary with local rates and deductions. Insurance and HOA dues vary by home.
Estimated monthly payment $3,119 Loan amount $405,000
Talk to a lender I trust
Good to know

The parts nobody explains.

What is earnest money?

A good-faith deposit you make when your offer is accepted, held by the title company and credited toward your purchase at closing. The amount is negotiable, and the contract spells out when you could get it back.

How do inspections work?

After your offer is accepted, you get a set number of days to inspect. Then we can ask the seller to repair, give a credit, or adjust the price, or you can walk away within the contract terms. I help you decide what’s worth asking for.

What’s an appraisal, and what if it comes in low?

Your lender orders an appraisal to confirm the home is worth the loan. If it comes in low, we have options: renegotiate, cover the gap, or challenge it with better comps.

What are closing costs?

Lender fees, title insurance, prepaid taxes and insurance, and recording fees. They’re separate from your down payment, and your lender gives you a Loan Estimate early on.

What’s a title commitment?

The title company’s report on who owns the home and what’s recorded against it. I have a one-page cheat sheet that walks you through reading one.

Don’t forget the homestead deduction

Once you move in, file for the homestead deduction on your primary residence. It lowers your property tax bill, and I’ll remind you how.

My trusted list

I know a guy. Several, actually.

Local pros I’ve vetted or worked alongside. Ask and I’ll send names and numbers.

Mortgage lendersHome inspectorsRadon & sewer scopeInsurance agentsTitle companiesMoversHandymenHVAC & plumbingElectriciansPaintersCleanersLocksmiths
Buyer questionnaire

Let’s get started.

Five quick sections, about four minutes. Your answers come straight to me, and I’ll reply within one business day.

  1. 1Let’s get acquainted
  2. 2Your situation
  3. 3What you’re looking for
  4. 4Financial picture
  5. 5About you
STEP 1 OF 5

Let’s get acquainted

How do you prefer to be contacted?
When are you generally available?
Rather just talk?

Text me.